This article draws on Keystone Consulting Team’s original page. Keystone Consulting Team is part of the SCALZ client network. The original source is identified so you can check the context.
Related service or subject: How payment processor holds affect cash flow and founder decisions from Keystone Consulting Team.
Fractional CFO vs CPA: Which gap needs support first?
Choose support by the unanswered question. A bookkeeper's records can be current yet a business finance decision remains unresolved. Keystone's fractional CFO vs CPA guide supplies a starting distinction: accounting treatment and business use raise different questions. The machine purchase below is hypothetical. It follows those questions from scope through cash and project reviews.
Keystone's role comparison describes CPA work as tax, accounting, and reports within an agreed scope. CFO work uses those facts to help owners weigh future choices. Some CPAs provide both kinds of support. The machine example therefore begins with the existing agreement. A task list shows what is covered. It avoids assuming that every CPA makes forecasts or that every CFO's work includes tax. The source also sets out the role of credentials. A CPA holds a state-issued license. The fractional CFO title alone does not prove a license is held. Some people in that role are also CPAs. Scope and credentials each need their own check.
Your current team may be enough if it gives clear, useful answers. Keystone's guide cites steady cash needs, clear margins, and few major choices. Does your CPA's scope already cover the questions behind your next big decision?
The timing of the work matters too. Tax work may follow a filing deadline. A hiring or equipment choice has its own due date. Keystone says CFO work should follow the business's needs. An owner can compare when each review takes place and who joins it. Will the facts be ready in time? A quarterly report may arrive after a large purchase. It serves a different need from a review held before the owner commits cash.
Consider a hypothetical founder who wants to buy a machine next month. The CPA has supplied a recent financial statement. Several customer balances are still unexplained. A forecast based on those balances would rest on the same unknowns. Keystone says late or incomplete records may need work first. Adding another adviser may have to wait. Here, the first task is to resolve the entries. The later cash review can then start with amounts the team can explain. The machine decision remains open while that work is done.
A brief comparison record could show the difference in the two outputs. In this hypothetical case, the accounting review says, 'Customer balance checked against invoices; one receipt remains held by the processor.' The cash review says, 'That held receipt is excluded from funds available for the machine payment.' The first explains an entry in the records. The second applies that fact to the purchase. Neither line stands in for the other. The owner can see how the two reviews connect without paying for the same work twice.
- Current agreement: retain the scope and fee terms for the comparison.
- Purchase record: use the machine's actual price and payment terms.
- Decision note: record the date by which the owner needs an answer.
Should cash choices use reported profit or available funds?
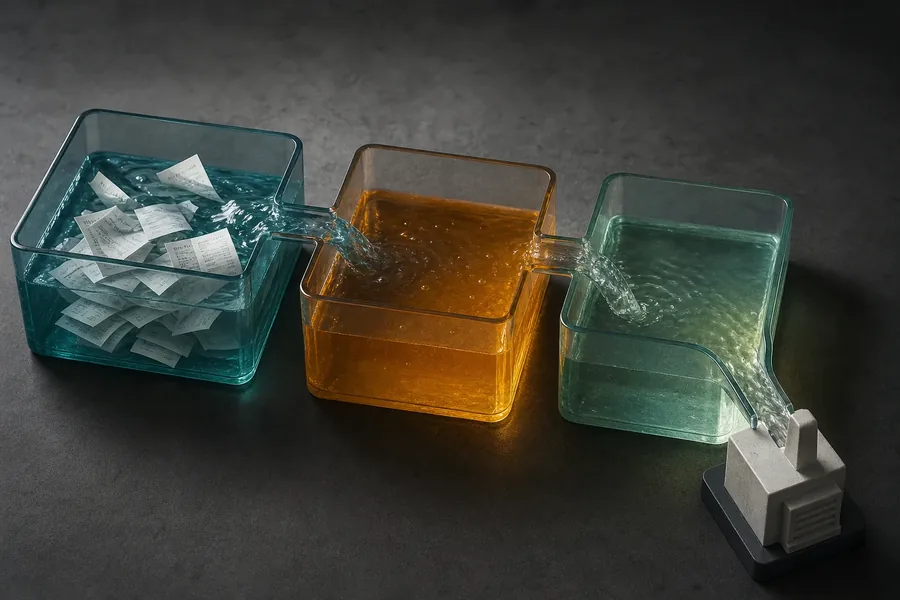
Can the business fund the machine on its payment date? A cash management review tests which receipts can pay the bills, while financial reporting explains how the sale and held funds belong in the accounts. A customer payment can therefore appear in the records before it is ready to spend.
Keystone's processor guide adds a specific case: a customer has paid, but the processor still holds the funds. The machine payment must be tested against the money the business can use when that payment falls due.
For held receipts, the reporting question is how the transaction and balance should be treated in the accounts. That belongs in the CPA's review within the agreed scope. The planning question is what the owner can fund while cash remains held. The processor guide separates pending, available, reserved, and paid-out balances. A founder can use those labels to describe the event to both advisers. One dashboard figure does not settle both questions.
In the planning example, suppose the customer receipt is $8,000 and still pending. The amount is known. The bank deposit date is not firm. The machine payment falls due before the processor's proposed review date. Under that timing case, the receipt cannot cover the payment. Keystone calls for tests of delayed and partial releases. The comparison would also show what changes if funds arrive later than hoped.
Now suppose $3,000 of that receipt reaches the bank while $5,000 remains held. The partial release changes the amount available for the purchase. It does not settle the full receipt. Keystone's partial-release case does not assume the rest follows at once. The forecast can show the $3,000 on its supported deposit date. The other $5,000 stays outside spendable cash. This shows the effect of the first payout. It makes no promise about the next one.
Refunds, fees, and reserve changes can explain a lower deposit as well. Keystone's guide describes a reconciliation from gross payments to actual bank deposits. If a deduction reduces the payout, moving the date alone would leave the forecast wrong. The business is waiting for less cash, not simply waiting longer. The reconciliation supplies the amount after those adjustments. The forecast then applies it to the period when it can fund the machine or other bills. This is where the accounting detail changes the purchase comparison.
A processor notice adds another kind of evidence. A date for reviewing the account is not a date for transferring money. Keystone warns owners to keep that distinction clear. In the example, a notice confirming a review would leave the deposit uncertain. A later payout confirmation would support a different entry. The communication file holds the document requests, submissions, and written confirmations behind those changes. A reader can then trace the forecast date to the processor's words. They need not rely on a remembered conversation.
- Processor statement: retain the balance labels and the statement date.
- Bank record: match each deposit to its supporting payout details.
- Communication file: keep document requests, submitted items, and written confirmations together.
Should a promising project take priority over other uses of cash?
Does the proposed job need cash or people already promised to other work? Bookkeeping and CFO support connects cost records with that choice, while business planning considers competing uses of those resources. For the machine purchase, both jobs belong in the review even if the new one has an attractive margin.
A purchase provides another test of scope. Keystone uses equipment to show how one act can raise accounting, tax, funding, and operating questions. Whether an expense is deductible is a CPA question. Whether the business should commit cash to it also needs a business review. An expense might receive one accounting treatment. That does not prove it is the best use of funds. No tax result is assumed here.
The machine also needs a stated purpose. Suppose the founder wants it for a proposed customer job. The review can show when that job needs materials, when labor must be paid, and when the customer is expected to pay. Keystone's cash guidance notes that upfront spending may precede customer receipts by some time. A positive margin would not, by itself, bridge that interval.
An owner can make the comparison clearer with three columns: the proposed job, existing work, and shared resources. Put labor, materials, and expected receipt dates against the relevant work. A shared resource appears once with an explanation of the competing need. The point is not to create an approval score. It is to expose assumptions. These can be easy to miss when each job is examined on its own. The firm's actual cost records would still be needed to fill the comparison.
Keystone supplies no universal margin target or project approval rule. Those judgments remain tied to the firm's costs, cash timing, and owner priorities. Its framework is for business choices, not specific investment advice. An adviser needs to explain tradeoffs and missing facts. Accounting treatment and tax effects still require confirmation with the owner's CPA before acting on a proposal.
A higher machine price changes the cash needed, while a later delivery changes when the new job can begin. If another job uses the available labor, the staffing plan changes even when the price and delivery date stay fixed. A revised comparison can name the changed input beside its effect on the job. That keeps the discussion on the affected cost, date, or staff need instead of reopening every part of the purchase plan.
- Compare the proposed job's delivery needs with work already promised.
- Show where both jobs need the same labor or cash.
- Separate changed costs from shifts in the timing of receipts.
- State the machine's purpose before weighing the purchase.
How can owner cash needs and a future exit share useful groundwork?
Some record work can support current cash needs and a possible exit. A fractional CFO can connect operating priorities with planning around ownership change. Keystone's role guide considers both uses. A balance that is hard to explain today could also complicate later scrutiny; resolving it may serve both purposes without making them identical.
Personal cash needs and business cash needs can pull in different directions. Keystone separates pay for work, ownership-related payments where relevant, and household needs. It says entity type, ownership arrangements, and applicable rules affect the appropriate structure. Keep those needs visible. Every transfer is not the same kind of payment, and personal and company funds are not one pool. The labels alone do not establish the appropriate structure.
Short-term cash pressure may call for a review of planned owner payments. Keystone expressly raises that choice when funds remain restricted. It also says salary, distributions, reimbursements, and other payments can have different tax and accounting effects. The work plan should show when the CPA reviews a proposed change. It should also note where legal guidance is needed. One role should not silently inherit every question.
Daily cash planning and buyer review use different time horizons. The owner needs a current view of receipts and bills before the next payment falls due. A buyer may compare several reporting periods to judge where profit comes from. Keystone names reporting timeliness and consistent cost categories as areas to watch. A late report can leave today's cash review short of facts; shifting cost categories can make two periods hard to compare even when both reports arrived on time. Those are separate record-quality issues.
The records needed also differ. For the machine decision, bank activity and processor statements help the team establish what cash is usable now. For later buyer scrutiny, Keystone's processor guide calls for agreements, reserve terms, reconciliation schedules, and records of major restrictions. Together, those files preserve the history behind the balances, including unresolved conditions. The buyer can examine whether a restriction was isolated or part of an ongoing problem, rather than relying on one day's available-cash figure. Unresolved balances still need to be explained, not removed from view.
Keystone also identifies dependence on the founder as a subject of buyer scrutiny. A person taking over the reporting needs enough detail to follow collections and update the forecast without rebuilding the story from the owner's inbox. That is a different test from whether the founder personally understands this month's machine payment. The work can start before a sale date is set, using checks that fit the firm's existing accounting process. Preparation cannot promise a sale or a valuation, and the CPA and attorney still need to review proposed transaction treatment.
- Needed now: facts for the next operating decision and their owner.
- Possible exit: records a buyer could review before a future sale.
- Shared groundwork: one scope for balances or costs serving both goals.
- Specialist review: CPA and legal input on proposed owner payment changes.